Suffolk Historic District (Boundary Increase II)

Why it's listed
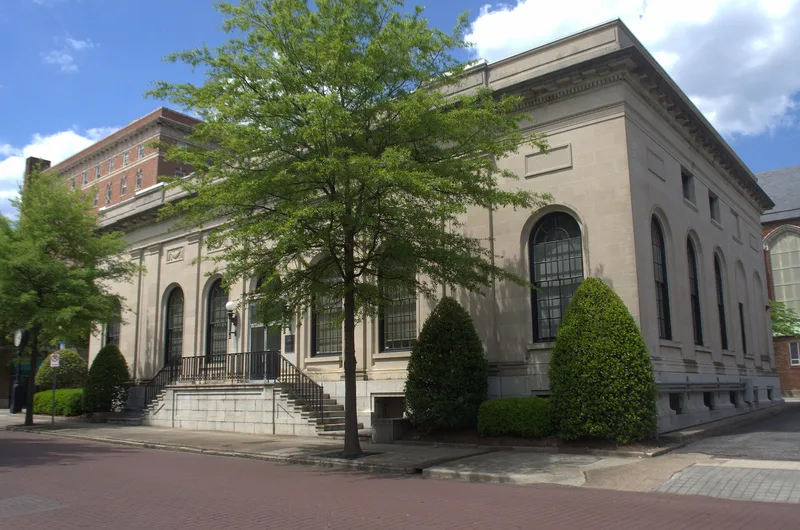
This boundary expansion brings the blocks south of Market and Bank Streets in downtown Suffolk, Virginia, into the Suffolk Historic District. The roughly 52-acre area holds 141 resources, including brick commercial buildings, warehouses, banks, two railroad depots, service stations, a courthouse and small groups of houses along Clay, Pinner and Liberty Streets. Most storefronts date from the early 20th century and show Italianate, Colonial Revival or plain commercial forms, with large plate-glass display windows and recessed entries. Taller landmarks include the seven-story Renaissance Revival National Bank of Suffolk and the Classical Revival Jones Building. The railroad shaped the area's growth, and a wooden depot from the late 19th century and a Tudor Revival depot survive. The area was found to share the original district's development and styles and to retain integrity. It was added for its architecture, commerce, industry and transportation, and the district's period of significance now runs to 1950.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1785-1950 |
|---|---|
| Styles | Late Victorian (Queen Anne, Italianate, Second Empire, Gothic Revival, Renaissance Revival), Colonial Revival, Classical Revival, Tudor Revival, Modern Movement and Commercial Style |
| Areas of significance | Architecture, Commerce, Industry, Transportation |
| Acreage | 52.6 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Suffolk Historic District (Boundary Increase II) (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.