Stuart Addition Historic District

Why it's listed
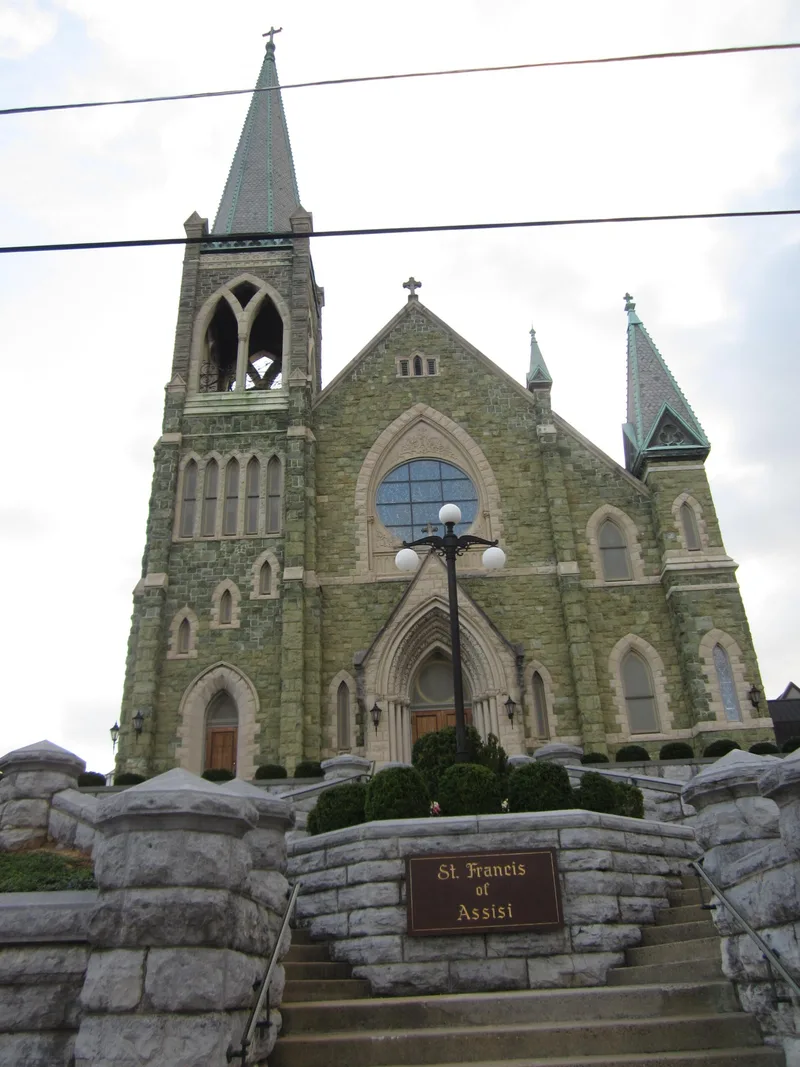
North of Staunton's downtown lies a medium-density residential neighborhood laid out in 1803, when Judge Archibald Stuart deeded the land to the city to be divided into streets and lots. The streets still follow that plan, and some old brick sidewalks and stone curbs remain. The district covers 23.24 acres and includes 105 structures. Its buildings range from substantial brick homes built for merchants and professionals to simple frame workers' cottages. At least seven vernacular dwellings predate 1825, among them a log structure from about 1800 that once served as a stagecoach stop and a brick Federal duplex from about 1810. Italianate houses are common, and other styles appear in individual examples. Local architect T.J. Collins designed St. Francis of Assisi Catholic Church, Mt. Zion Baptist Church and the Chateauesque C.W. Miller House, which is separately listed. Four churches line Augusta Street, which also holds the commercial uses. Most houses are now apartments, though exterior changes have been modest.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Styles | Mostly vernacular and Italianate, with examples of Gothic Revival, Chateauesque, Georgian/Colonial Revival, Federal, Queen Anne, Shingle Style and Bungalow |
|---|---|
| Areas of significance | Education, Architecture, Religion, Social History |
| Acreage | 23.3 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Stuart Addition Historic District (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.