Broad Street Commercial Historic District (Boundary Increase II)

Why it's listed
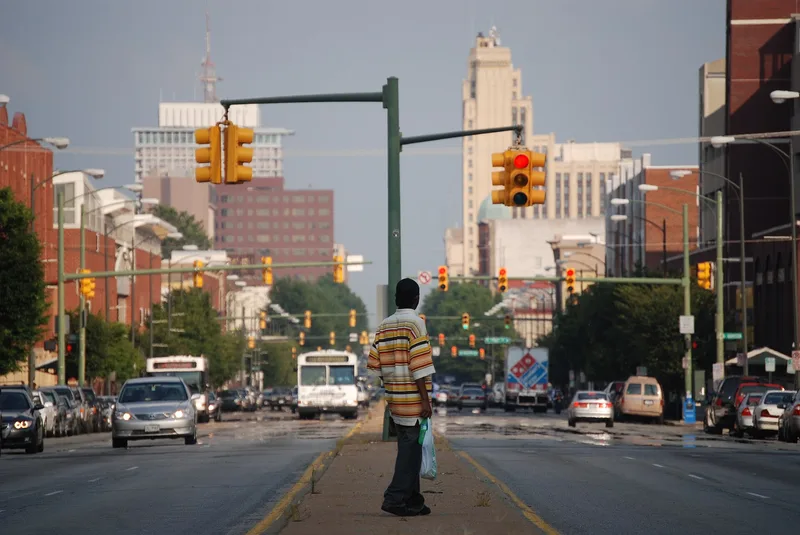
This boundary increase extends Richmond's Broad Street Commercial Historic District north into two half-blocks bounded by Marshall, First and Second Streets. It holds eight contributing buildings and one non-contributing building, mostly two-story brick structures with storefronts, decorative cornices and revival or vernacular commercial detailing. Maps and directories show the area was largely residential with a few small businesses in 1895 and 1905. Commercial uses then spread, and by 1924 the change from houses to businesses south of Marshall Street was complete. Shops included a bicycle repair shop, an auto garage, billiard parlors, a restaurant and specialty stores, though they were less stylish than those on Broad and Grace Streets. One surviving dwelling at 313 North 2nd Street, with a later storefront addition, recalls the earlier neighborhood. Architects represented include Henry T. Barnham, Luther T. Bengston and Davis Brothers. The demolished St. Luke Penny Savings Bank, designed by Charles Thaddeus Russell, is also part of the area's story. The period of significance runs from 1900 to 1925.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1900-1925 |
|---|---|
| Styles | Commercial; Late 19th and 20th Century Revivals |
| Areas of significance | Architecture, Community Planning and Development, Commerce |
| Acreage | 2 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Broad Street Commercial Historic District (Boundary Increase II) (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.