Cooper, A.S., Farm

Why it's listed
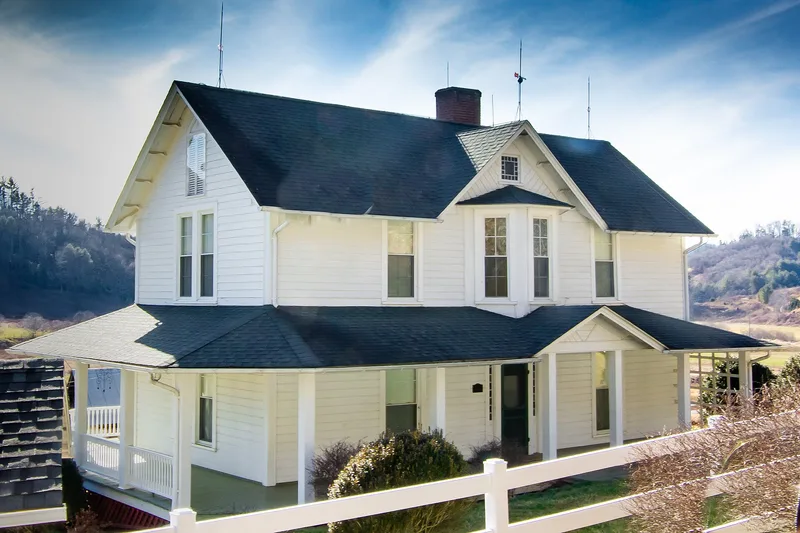
Set in a narrow valley of the Blue Ridge Mountains near the South Fork of the New River, this farm straddles the Ashe and Watauga county line. Buildings are grouped in three clusters: the homeplace built around 1890 by A.S. Cooper, Sr., a barn complex, and a group around the c.1880 Phillips house. The centerpiece is a two-story late Victorian I-house with a wrap-around porch, stained glass and sunburst corner blocks. Nearby are a spring house, granary, barns, concrete silos, a 1946 milking parlor, two 1955 chicken houses and a family cemetery of eighteen graves dating from about 1860. The fields, pastures, woodlands and springs follow the slope of the land. The farm was listed because it shows how a Blue Ridge farm moved from subsistence crops and livestock to dairy and poultry production in the mid-twentieth century, and because its buildings represent local architecture from about 1880 to 1946. The Cooper family has continued to farm it.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | c. 1880-1951 (agriculture); c. 1890-1946 (architecture) |
|---|---|
| Styles | I-House (late Victorian) |
| Areas of significance | Agriculture, Architecture |
| Acreage | 180 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Cooper, A.S., Farm (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.