Matton Shipyard

The National Park Service has not published a boundary polygon for this district; the map shows the listed properties inside it and the district's reference point.
Why it's listed
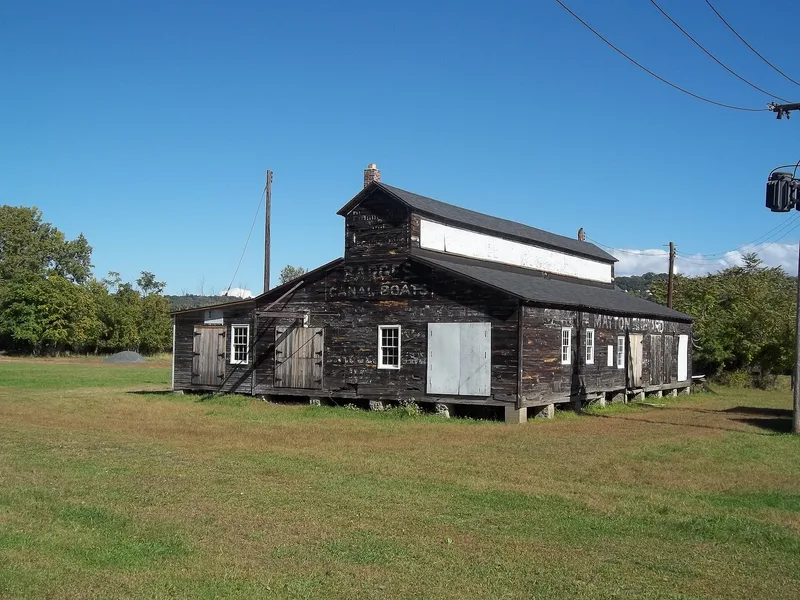
Matton Shipyard occupies about four acres near the northern tip of Van Schaick Island in Cohoes, close to where the Hudson and Mohawk Rivers meet. John E. Matton bought the land in June 1916 to take advantage of the new Barge Canal, and the yard built and repaired canal boats and tugs. It began with seven buildings, a dock, a track-mounted crane and a floating dry dock. During World War I it held a contract for fourteen wooden barges. It grew in the 1930s, built its first all-steel boat in 1938, and expanded again in World War II, when a security fence was added. Eight buildings survive, including the office and the carpenter shop with its monitor roof and clerestory windows, along with launching ramps, a dock and mooring camels. Its significance rests on commerce, maritime history, transportation and manufacturing between 1916 and 1959.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1916-1959 |
|---|---|
| Styles | Other: Industrial |
| Areas of significance | Commerce, Maritime History, Transportation, Industry |
| Acreage | 4.1 |
| Boundary source | not published |
| Full listing page | Matton Shipyard (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.