Lansing Manor House

Why it's listed
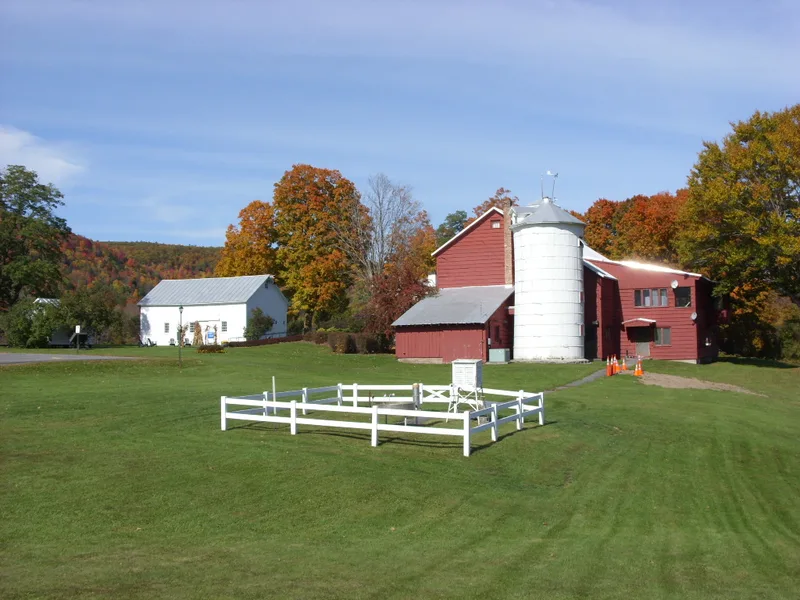
Lansing Manor House is a two-story hipped-roof house of about 1818, set on a plateau overlooking Schoharie Creek about two miles south of North Blenheim. It has a brick-lined frame first story, a wood frame second story, lapped siding, and a five-bay porch across the front. Notable details include a fanlight at the entrance and a small oval window on the south side. Nine original fireplaces still work, and a cellar holds the original kitchen and servants' quarters. Farm outbuildings include a summer kitchen, ice house, milk house, barn and silos. John Lansing Jr., a former Chancellor of New York, gave the property to his son-in-law Jacob Sutherland, a lawyer sent to manage the estate, and the house was built for him and his family. The property lies within the Blenheim Patent of 1769 and later saw anti-rent activity. It operated as a livestock and grain farm into the twentieth century, and the house has changed little since its construction.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 19th Century (specific date c. 1800 noted) |
|---|---|
| Areas of significance | Politics/Government, Architecture |
| Acreage | 300 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Lansing Manor House (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.