Shirley Center Historic District

Why it's listed
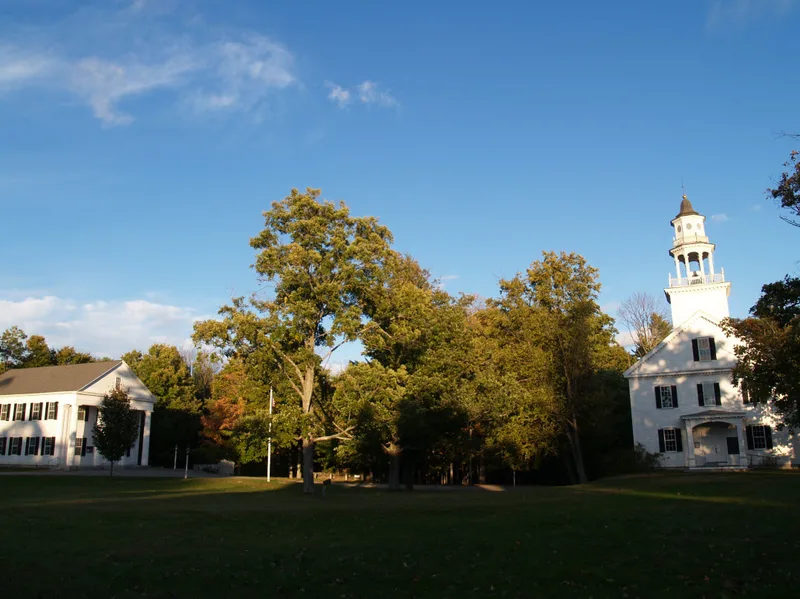
Shirley Center is the earliest settlement core of Shirley, Massachusetts, a 72-acre area of farmhouses, civic buildings and open spaces arranged around the Town Common. Most of the 42 contributing resources are residential, from the 1755 Adams House to Federal, Greek Revival and Italianate dwellings, with a single 1920s bungalow. Institutional landmarks include the First Parish Church, first built in 1773 and moved and remodeled in 1851, and the Greek Revival Town Hall of 1848. The Center Cemetery, the Town Pound and the Common itself are also part of the district. The area was listed for its local importance in architecture, community planning and agriculture between 1753 and 1930. After Shirley separated from Groton in 1753, the Center remained the civic hub while mills and the railroad grew up to the south. That isolation preserved the curving roads, stone walls, mature trees and irregular building setbacks of a rural farming community.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1753-1930 |
|---|---|
| Styles | Colonial: Georgian; Early Republic: Federal; Mid-19th Century: Greek Revival; Late Victorian: Italianate; Bungalow |
| Areas of significance | Community Planning and Development, Agriculture, Architecture, Social History |
| Acreage | 72 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Shirley Center Historic District (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.