Tifton Commercial Historic District

Why it's listed
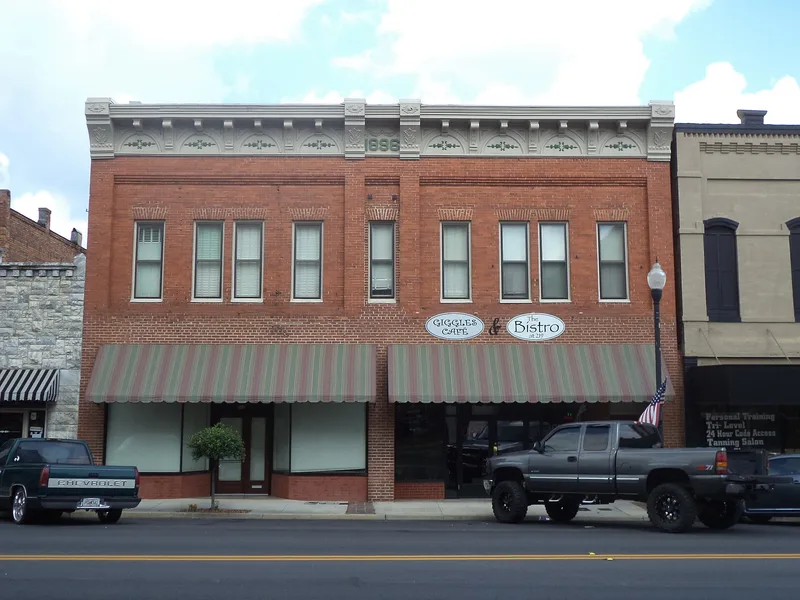
Downtown Tifton's commercial core, covering about 35 acres across portions of ten blocks, reflects the town's growth around two crossing railroads. Henry Harding Tift bought timberland in 1872 and started a sawmill, and a second railroad arrived in 1888. Tifton was incorporated in 1890 and became county seat in 1905. Most buildings are brick, one to three stories, dating from the 1890s to the late 1930s, with a near halt in construction between 1925 and 1935. Victorian Eclectic and Early 20th Century Commercial styles dominate. Landmarks include the 1906 Myon Hotel, the 1912 Tift County Courthouse, the 1914 post office (now the library), the 1916 Union Station, the 1917 Bank of Tifton, the Twin Brick Warehouses, and two 1937 Art Deco and Art Moderne buildings, the Lockeby Building and Tift Theatre. Three railroad depots and several warehouses document the town's role as a shipping and marketing center for the surrounding farm country.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1890s - 1925; 1937 |
|---|---|
| Styles | Victorian Eclectic and Early 20th Century Commercial, with Georgian Revival, Neoclassical, Beaux Arts, Renaissance Revival, Prairie, and Art Deco/Art Moderne influences |
| Areas of significance | Politics/Government, Commerce, Architecture, Community Planning and Development, Transportation |
| Acreage | 35 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Tifton Commercial Historic District (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.