Stuart Uptown Historic District

The National Park Service has not published a boundary polygon for this district; the map shows the listed properties inside it and the district's reference point.
Why it's listed
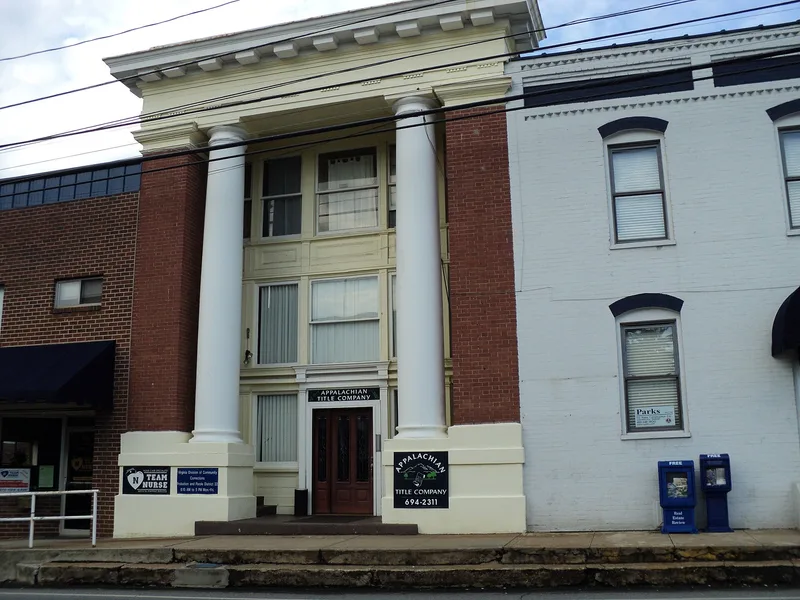
Stuart's uptown district covers about six acres at the junction of Main Street and Blue Ridge Street in Patrick County, Virginia. It began as the village of Taylorsville, which grew around the county courthouse after 1792, and was renamed Stuart when the railroad arrived and the town incorporated in 1884. The district centers on the brick courthouse of 1858/59, designed by C.Y. Thomas, with Greek Revival detailing later altered with Colonial Revival features. Nearby are the ca. 1911 Patrick County Bank, with its colossal columns, the Stuart Baptist Church, the Gothic Revival Methodist church, and a 1940 post office built by the Works Progress Administration. Main Street's one- and two-story brick shops include the 1938 Stuart Drug Store, the town's only commercial Art Deco building. The district was recognized for its local importance in government, commerce and architecture between 1858 and 1951. Of the buildings in the district, most contribute to its historic character, although some storefronts have been modernized.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1858-1951 |
|---|---|
| Styles | Classical Revival, Gothic Revival, Colonial Revival, Art Deco |
| Areas of significance | Politics/Government, Commerce, Architecture |
| Acreage | 6 |
| Boundary source | not published |
| Full listing page | Stuart Uptown Historic District (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.