Hopefield

Why it's listed
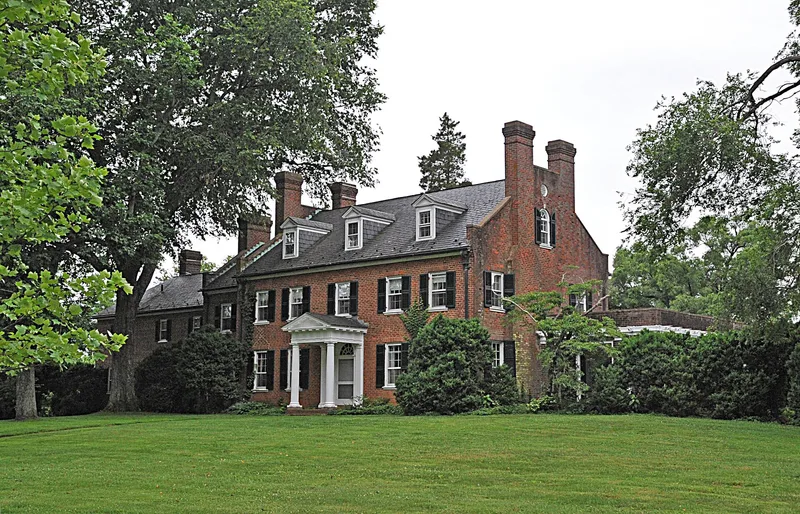
Hopefield is a 168-acre country estate north of Warrenton, Virginia, on the banks of Cedar Run. Its centerpiece is a five-bay brick house begun about 1855 as a two-story Federal-style I-house. In 1924 architect W. H. Irwin Fleming and the Hanback builders enlarged it, raising the roof, adding dormers, a Doric portico and side wings, and turning it into an asymmetrical Colonial Revival residence. Fleming also laid out the grounds, including a stone ha-ha wall concealing a pump house, boxwood-enclosed gardens, a bowling green and a swimming pool. Earlier farm buildings survive: a summer kitchen, an icehouse with an iron door, a drive-in crib barn extended in 1924, and a ruined house of about 1890. A brick garage and a tenant house were added by about 1950. The Wallach family owned the estate from 1924, and the buildings and landscape kept exceptional integrity, supporting a period of significance from 1855 to 1950 in architecture and landscape architecture.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1855-1950 |
|---|---|
| Styles | Late 19th and 20th Century Revival: Colonial Revival; Other: Federal Revival |
| Areas of significance | Architecture, Landscape Architecture |
| Acreage | 168.4 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Hopefield (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.