Mandeville Mills and Mill Village Historic District

Why it's listed
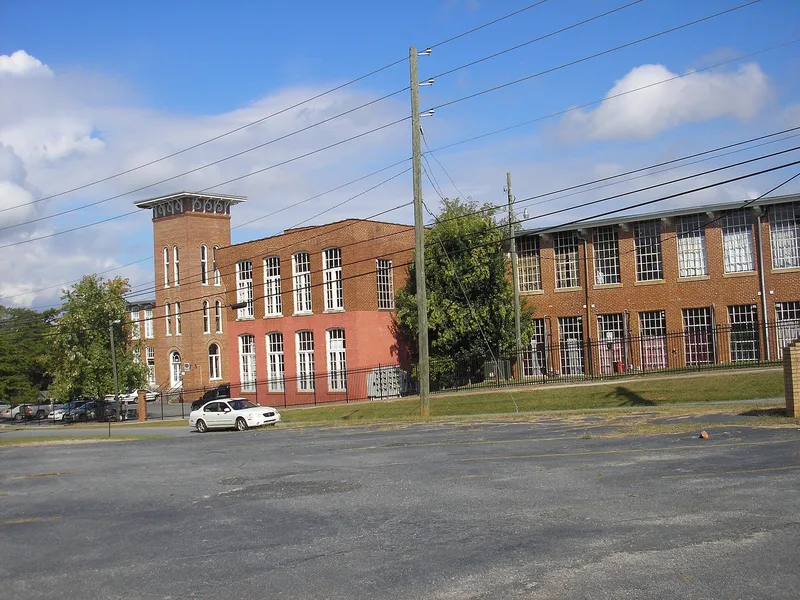
Mandeville Mills and Mill Village Historic District occupies land west of downtown Carrollton, Georgia, and combines an industrial complex with the neighborhood built for its workers. The Carrollton Oil Mill was organized in 1898 and Mandeville Cotton Mill in 1899. They merged in 1902 as Mandeville Cotton Mills, Inc. The brick Mill #1 dates to 1900, and Mill #2 followed in 1908. The mills stand along the Central of Georgia rail line, and oil mill buildings such as gins, seed and meal houses and a warehouse sit to the east. Around them, the village was built in two phases, with one-story wood-frame houses on tree-lined streets that keep their original layout. House types include shotgun, double shotgun, saltbox, pyramid cottage and bungalow. Two churches and three stores also survive. The district was recognized for its architecture, its planned community, its industrial role and its social history between 1898 and 1953. In 1949 the company began selling village property, and the mill was sold in 1953.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1898-1953 |
|---|---|
| Styles | Folk Victorian, Commercial, Craftsman, Hall-Parlor, Extended Hall-Parlor, Saltbox, Bungalow, Georgian House |
| Areas of significance | Architecture, Community Planning and Development, Industry, Social History |
| Acreage | 180 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Mandeville Mills and Mill Village Historic District (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.