Ashburn Commercial Historic District

Why it's listed
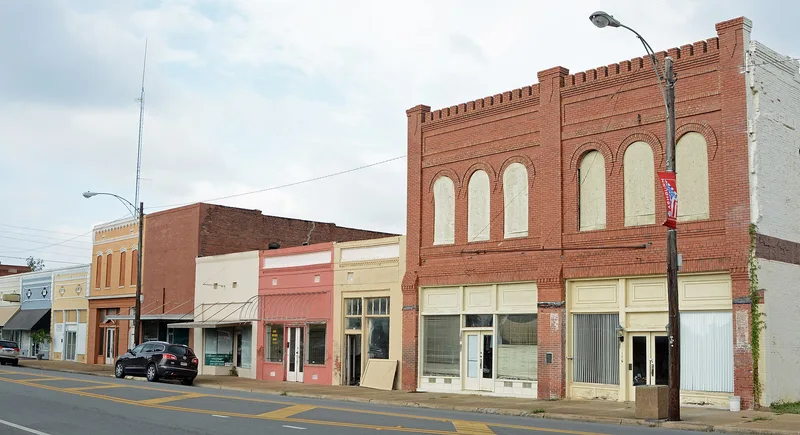
Ashburn's historic downtown is a small-town business district in Turner County, Georgia, laid out along the railroad tracks. The district covers about 16 acres and includes brick storefronts, two early banks, a gas station, warehouses, the county courthouse, the county jail and a 1939 post office. Across the tracks are a peanut oil mill warehouse, waterworks structures and the city's first jail. The railroad reached Ashburn in 1888, and a railroad survey in 1889 set out the rectangular block pattern; architect Peter E. Dennis enlarged the town plan in 1898. The buildings show styles such as Victorian Commercial, Stripped Classical, Neoclassical Revival and Spanish Colonial Revival, with details including brick corbeling, cast-iron columns, transom windows and wooden awnings with brackets. The district was listed for its intact architecture and for its role in the town's commerce, industry, transportation and government between 1889 and 1942. Its stores continue to serve the community.
Machine-generated summary. This summary was generated by a language model from the official nomination document and has not been reviewed line by line by an editor. It may contain errors. Check the source document before relying on any detail. Source: nomination document (PDF) · catalog entry. Generated October 2026 (model claude-sonnet-5-5, prompt v1.0-2026-10-29).
| Period of significance | 1889 - 1942 |
|---|---|
| Styles | Late Victorian: Romanesque; Commercial Style; Spanish Colonial Revival; Neoclassical Revival |
| Areas of significance | Industry, Community Planning and Development, Commerce, Transportation, Politics/Government, Architecture |
| Acreage | 16 |
| Boundary source | NPS cultural-resource GIS polygon |
| Full listing page | Ashburn Commercial Historic District (property record) |
What listing means for this property
This is a historic district. Buildings within its boundary are either contributing (they add to the district's significance) or non-contributing. Owners of contributing income-producing buildings can claim the 20% federal rehabilitation tax credit; homeowners should look at state credits. National Register districts impose no design review by themselves; a local historic district ordinance, if one exists, does (the difference explained).
General information, not legal or tax advice. Rules change; confirm with your State Historic Preservation Office or a qualified adviser.